
How Real Estate Investors Can Defer Capital Gains and Reposition Their Portfolio

By Betty Wang Real Estate Team
Selling an investment property can create an interesting dilemma.
You may have built substantial equity and be ready to move on—but selling can also trigger capital gains taxes and depreciation recapture, potentially reducing the amount of capital available for your next investment.
For some property owners, a 1031 exchange can provide another option.
Rather than selling, paying the applicable taxes immediately, and then investing what remains, a properly structured 1031 exchange may allow you to defer certain taxes by reinvesting the proceeds into another qualifying investment property.
It is not a loophole, and it is not simply a tax strategy. Used thoughtfully, a 1031 exchange can become part of a much larger real estate and wealth-planning strategy.
What Is a 1031 Exchange?

A 1031 exchange takes its name from Section 1031 of the Internal Revenue Code.
In simple terms, when qualifying real property held for investment or business purposes is sold and replaced with other qualifying real property, the owner may be able to defer recognition of some or all of the gain.
The important word is defer.
A 1031 exchange generally does not make the tax disappear. Instead, the tax basis is carried into the replacement property, subject to the applicable rules and adjustments.
Why does that matter?
Because the capital that might otherwise have been used to pay taxes immediately can potentially remain invested in real estate.
For a long-term investor, keeping more capital working can have a meaningful effect over multiple transactions.
“Like-Kind” Is Broader Than Many Investors Think
One of the biggest misconceptions about 1031 exchanges is that you must exchange one property for an identical property.
You don't.
For qualifying real estate, “like-kind” is generally much broader.
An investor may potentially sell an apartment building and acquire an industrial property. A rental house could potentially be exchanged for commercial property. An owner might sell one larger investment and acquire multiple replacement properties—or consolidate several investments into a different asset.
The question is generally not whether the properties look alike.
The more important issue is whether the properties satisfy the requirements for qualifying real property held for investment or productive use in a trade or business.
This flexibility is one reason a 1031 exchange can be particularly useful when an investor's goals begin to change.
The Two Deadlines You Cannot Ignore
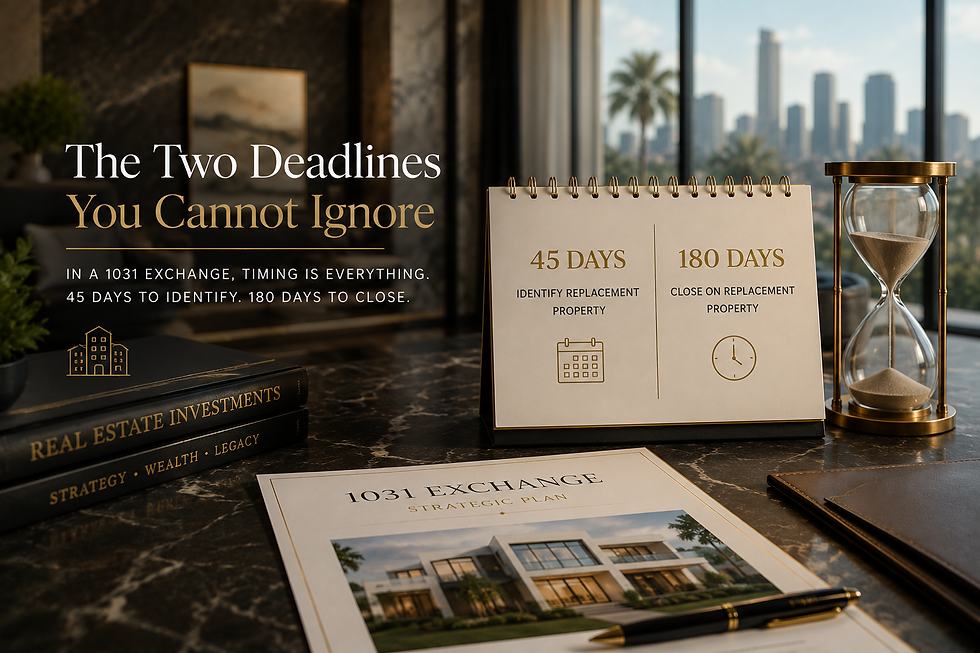
A 1031 exchange is highly dependent on timing.
After the relinquished property is sold, two deadlines become particularly important:
45 days: The investor generally has 45 calendar days to formally identify potential replacement property.
180 days: The replacement property generally must be acquired within 180 days of the sale of the relinquished property—or by the due date of the applicable tax return, including extensions, if earlier.
These periods run concurrently.
That means the 180-day period does not begin after the 45-day identification period ends.
And because these are calendar-day deadlines, weekends and holidays generally do not give you additional time.
In a competitive market, 45 days can pass remarkably quickly. That is why I prefer clients considering a 1031 exchange to begin discussing replacement-property strategy before their existing property closes, rather than beginning the search on Day 1.
Why the Qualified Intermediary Matters

A traditional delayed 1031 exchange generally requires a Qualified Intermediary (QI).
The seller typically cannot simply receive the proceeds from the sale, deposit the money into a personal account, and later decide to complete an exchange.
The exchange needs to be structured properly, and the QI generally holds the proceeds between the sale of the relinquished property and acquisition of the replacement property.
This is an area where preparation matters.
Ideally, your real estate broker, CPA or tax advisor, attorney (when appropriate), escrow, and qualified intermediary should understand the intended structure before closing.
Trying to reconstruct an exchange after the sale has already closed may be too late.
Where Investors Commonly Get Into Trouble

The basic concept of a 1031 exchange is relatively easy to understand. The execution is where mistakes happen.
Common problems can include taking possession or control of sale proceeds, missing the 45-day identification deadline, missing the 180-day completion deadline, improperly identifying replacement properties, acquiring property that does not qualify, or misunderstanding how debt, cash received from the transaction, and other forms of “boot” can affect the tax result.
Another common mistake is allowing the tax strategy to drive the entire investment decision.
A replacement property should still make sense on its own merits.
I would rather see a client evaluate the location, income, expenses, tenant quality, lease structure, financing, future liquidity, and long-term potential than rush into a poor investment simply because the 45-day clock is running.
The tax strategy should support the investment strategy—not replace it.
A 1031 Exchange Can Also Be a Portfolio Strategy

This is where the conversation becomes more interesting.
Many investors initially think about a 1031 exchange only as a way to defer taxes. But as portfolios mature, it can also become a way to reposition assets.
For example, an owner who has spent decades managing several residential rental properties may eventually want less day-to-day involvement.
Another investor may want to move equity from an older asset with significant maintenance requirements into newer property.
Someone else may want to consolidate several smaller investments into one larger asset, diversify into different property types or geographic markets, or move from an appreciation-focused investment toward stronger income.
For long-term owners, the question is often no longer simply:
“Should I sell?”
It becomes:
“Where should this equity go next?”
That is a much more strategic conversation.
The Best 1031 Planning Often Begins Before the Property Is Listed
When I work with investment-property owners, I prefer to understand the larger objective before we decide how to market or structure the sale.
Are you trying to increase cash flow?
Reduce management responsibilities?
Move into a different asset class?
Consolidate your portfolio?
Diversify geographically?
Prepare for retirement or long-term estate planning?
Those answers can influence not only what replacement property we search for but also how we think about pricing, timing, and the overall transaction.
A 1031 exchange should not be treated as an isolated piece of paperwork at the end of a sale. When appropriate, it should be considered as part of the strategy from the beginning.
Real Estate Is Only One Part of the Conversation
As a real estate broker, my role is to help clients evaluate the real estate itself: the property, market, pricing, negotiations, timing, and potential replacement opportunities.
Tax and legal decisions belong with the appropriate professionals.
For clients considering a 1031 exchange, we can coordinate the real estate transaction with their CPA, tax advisor, attorney, and qualified intermediary so that everyone is working toward the same objective.
The goal is not simply to complete another transaction.
It is to make sure the next property makes sense for where the investor wants to go next.
Considering Selling an Investment Property?
Before putting the property on the market, it may be worth understanding whether a 1031 exchange should be part of your strategy—and what you might want to own next.
Contact Team Betty Wang to discuss your investment property and potential replacement property strategy.
Betty Wang | Associate Broker
DRE#01946131
Team Betty Wang
Where Art Connects People and Real Estate Builds Legacy
Luxury Real Estate • Strategic Investments Beverly Hills • Los Angeles • Pasadena
This article is provided for general informational purposes only and is not intended as tax, legal, accounting, or financial advice. Section 1031 transactions are subject to detailed federal tax requirements and individual circumstances. Consult your CPA, tax advisor, attorney, and qualified intermediary regarding your specific situation.


Comments